Video Analysis
Chief Economist Tom Orlik argues that higher interest rates are the 'new normal,' driven by structural shifts like demographic changes, reduced foreign investment in US debt, increased defense spending, and AI investments. He anticipates a Fed rate hike next week, which will increase borrowing costs and likely trigger political backlash from President Trump.
- Higher interest rates are the 'new normal' due to a fundamental shift from a global 'savings glut' to a 'dearth of saving' and increased investment demand.
- Key drivers of this shift include retiring baby boomers, reduced US Treasury purchases by China and petrostates, surging defense spending, and massive AI infrastructure investments.
- The upcoming Fed rate hike, expected by markets, will increase debt servicing costs for governments, businesses, and households, and could lead to political pressure on the Fed Chair from President Trump.
The discussion highlights renewed Houthi attacks on Saudi oil infrastructure, indicating a significant setback for US efforts to stabilize regional oil flows and suggesting closer coordination between Iran and the Houthis. Despite economic pressure, Iran is pursuing a strategy of regional dominance, as evidenced by these attacks and new construction at its nuclear facility, challenging the effectiveness of current US policy.
- Houthi attacks on Saudi oil pipelines, bypassing the Strait of Hormuz, disrupt the US narrative of stabilizing regional oil markets.
- The relationship between Iran and the Houthis is seen as much more significant and direct, with Houthis acting on behalf of Iran when necessary.
- Iran aims to establish a 'tributary system' in the Persian Gulf, asserting dominance over smaller Gulf states and controlling oil traffic, rather than seeking cooperation.
- Despite a depleted economy with high inflation, Iran's aggression is increasing, suggesting economic pressure is not an effective coercive tool for changing its strategic priorities.
- New construction at Iran's deeply buried Pickaxe Mountain nuclear facility raises concerns about the nuclear program's future and negates claims of its obliteration.
Saudi Arabia's East-West oil pipeline has been shut down as a precautionary measure following multiple attacks, raising concerns about global oil supply. This disruption, coupled with existing refining shortages and increased demand from countries like China, is expected to further tighten energy markets and drive up prices, particularly for diesel in the US.
- Saudi Arabia shut its East-West pipeline after multiple attacks, threatening a crucial route for crude oil.
- The pipeline's closure, even if precautionary, highlights the vulnerability of fixed energy infrastructure to geopolitical tensions.
- US diesel prices have risen past $6/gallon, driven by a combination of crude oil shortages and refining capacity issues.
- China's renewed oil purchases, after a period of reduced demand, are likely to exert further upward pressure on global oil prices.
- The BRICS summit, including major oil importers (China, India) and exporters (Russia, UAE), is noted for its potential influence on global energy dynamics, despite internal trade conflicts.
The video discusses OPEC's diminishing influence on global oil markets. Key factors include member states prioritizing immediate sales over production quotas, the UAE's departure, and Venezuela considering similar actions. This shift signals a precarious future for Saudi Arabia's ability to unilaterally sway energy prices.
- OPEC's historical control over global oil supply is weakening.
- Member countries are increasingly prioritizing individual sales over collective production limits.
- The UAE has already exited, and Venezuela is contemplating leaving, further eroding OPEC's unity.
- Saudi Arabia's power to influence energy markets through OPEC is becoming uncertain.
The discussion emphasizes the necessity of owning semiconductor stocks due to their integral role in AI, power, and memory. The analyst, Rich Ross, maintains a long-term bullish stance on technology, suggesting that recent market pullbacks offer unique buying opportunities, especially as the market has already discounted Fed rate hikes. Specific semiconductor and related tech stocks are highlighted as ripe for investment.
- Semiconductors (Semis) are a 'must-own' sector, driven by AI, power, and memory demands.
- Tech has historically outperformed the broader market in 4 out of 5 Fed hiking cycles, with recent drawdowns already pricing in hawkish Fed action.
- Specific stock recommendations include Lam Research (LRCX), Bloom Energy (BE), Lumentum Holdings (LITE), Micron Technology (MU), and Caterpillar (CAT).
The video highlights diverging AI strategies between the US and China, with US tech leaders advocating for caution while Chinese companies like DeepSeek and Moonshot AI aggressively release new models and target revenue growth. It also previews next week's central bank activity, including the FOMC, BOE, and BOJ meetings, alongside key economic data releases and Lennar's earnings.
- US & China AI strategies are diverging, with the US emphasizing caution and China accelerating development.
- DeepSeek released its new 4.1 Flash model, and Moonshot AI targets $2 billion in annual recurring revenue by 2026.
- Next week's focus includes central bank activity (FOMC, BOE, BOJ decisions) and economic data (retail sales, housing, manufacturing, China data).
- Lennar (LEN) earnings are expected on Wednesday.
Louis Vuitton, owned by LVMH, experienced a significant social media backlash and sales decline in China after winning a trademark dispute against local tea chain Molly Tea. Accusations of cultural appropriation and bullying a smaller brand led to estimated sales drops of 30% in July and 20% in August, impacting LVMH's performance in one of its largest markets.
- Louis Vuitton won a trademark court case against Molly Tea in June, leading to a major social media backlash in China.
- Chinese social media users accused Louis Vuitton of 'cultural appropriation' due to similar floral designs and being 'cheap' for suing a smaller local company.
- Sources indicate LVMH's China sales were hit hard, with declines of 30% in July and an estimated 20% in August, though the decline may have narrowed to 15% in September.
- UBS estimates that China accounts for 30% of LVMH's total sales, highlighting the significance of this market.
PIMCO economist Tiffany Wilding suggests that decelerating nominal wage inflation and non-accelerating unit labor costs, influenced by AI and demographics, allow the Federal Reserve to be more patient with rate hikes. She views current hikes as risk management, contrasting the current environment with the tighter labor markets of 2022.
- Nominal wage inflation is decelerating, and unit labor costs (wages adjusted for productivity) are not accelerating.
- AI and demographic shifts are contributing to modest wage pressures in the labor market.
- These factors provide the Federal Reserve with room to be patient and view current rate hikes as risk management, rather than aggressive tightening.
Carley Garner discusses the recent surge in crude oil prices, deeming the $10 rally in three days excessive. She identifies $105 as a critical resistance level and warns of potential price squeezing risk, but ultimately sees a path of least resistance lower due to demand destruction and historical patterns.
- The recent $10 crude oil rally was excessive and a sentiment shift, not fundamentally driven by supply cuts.
- $105 is a critical daily resistance level; a break above could attract inflation hedge money, but seasonality and demand destruction risks loom.
- High oil prices lead to consumer pullback and demand destruction, with historical precedents of rapid price collapses after spikes.
OpenAI CEO Sam Altman is reportedly open to slowing cutting-edge AI development, possibly in collaboration with other labs, in response to growing 'extinction' warnings from researchers. However, industry leaders like Y Combinator CEO Garry Tan dismiss these extreme fears, advocating for a focus on tangible, current risks rather than science fiction scenarios. The debate highlights increasing scrutiny on AI safety and its development pace.
- OpenAI CEO Sam Altman is reportedly considering slowing AI development due to 'extinction' warnings from researchers.
- A top OpenAI researcher published an essay, 'An Alien Mind,' arguing for stronger AI alignment to prevent rogue AI.
- Y Combinator CEO Garry Tan, an OpenAI investor, believes the 'extinction' fears are overblown, urging a focus on 'science fact, not science fiction.'
- The ongoing debate underscores growing concerns about AI safety and potential regulatory interventions.
Holly Newman Kroft of Neuberger discusses the market's reaction to the latest CPI data and the Federal Reserve's anticipated rate hike. She maintains a bullish outlook on the market, driven by strong corporate earnings and continued AI spending, despite expecting increased volatility. Her recommendations include focusing on high-quality small caps and emerging markets.
- The Federal Reserve is expected to hike rates next week, as the latest CPI data did not significantly alter expectations.
- Despite anticipated increased volatility from geopolitical events and elections, the market is seen as resilient due to strong corporate earnings and robust AI spending.
- Strategic asset allocation recommendations include overweighting high-quality small caps and emerging markets (e.g., China, Taiwan, Korea), and being slightly underweight on non-U.S. developed markets, particularly Europe.
The market is reacting positively to August's in-line CPI print, driven by the certainty of an upcoming Fed interest rate hike. Despite high diesel prices and contracting consumer sentiment, the market views the Fed's path as clear, potentially leading to a pullback in consumer spending that could help tame inflation.
- August CPI print came in mostly in line with expectations, leading to a market rally due to increased certainty about the Fed's next rate hike.
- Diesel prices have hit $6 a gallon for the first time ever, and gasoline demand is slightly above 2020 levels, indicating persistent energy cost pressures.
- Preliminary September consumer sentiment data from the University of Michigan shows contractionary territory (47.8), with low current conditions and expectations, which the Fed might view as a positive for taming inflation.
The video discusses the August CPI report, attributing firming headline inflation to rising oil prices. The economist highlights a weakening labor market and increasing consumer financial stress, advocating for the Fed to hold interest rates next week as further hikes would exacerbate consumer hardship and are ill-suited for supply-driven inflation.
- August CPI showed firming headline inflation, primarily driven by rising oil, gasoline, and diesel prices (supply-side issue).
- The labor market is showing signs of weakness with low hiring/quits, increased long-term unemployment, and slipping real wage growth.
- Consumers are experiencing 'inflation fatigue' and financial stress, evidenced by rising credit card delinquencies for younger borrowers and housing affordability issues.
- The economist advocates for the Fed to hold interest rates next week, as further hikes would exacerbate consumer hardship and are not an appropriate response to supply-driven inflation.
This video is a promotional announcement for Schwab Network's special coverage of an upcoming FOMC interest rate decision and Fed Chair Kevin Warsh's press conference. It highlights current market conditions, including spiking oil prices and multi-year high interest rates, and emphasizes the potential impact of the Fed's decision on inflation, the economy, and markets.
- Schwab Network will provide live coverage and analysis of the FOMC interest rate decision.
- The broadcast will feature Fed Chair Kevin Warsh's live press conference and full market reaction.
- Current economic conditions include spiking oil prices and multi-year high interest rates, making the Fed's decision highly anticipated.

The video discusses rising US Treasury yields, with the 10-year nearing 5% and 30-year bonds reaching a 25-year high, despite a disappointing Treasury debt buyback. Concerns are amplified by renewed inflation pressures and increased bets on a Fed rate hike. President Trump's proposed $1.3 trillion 'dividend' further rattles bond investors, raising fiscal deficit concerns.
- US 10-year Treasury yield creeps closer to 5%, highest in nearly three years.
- Treasury's debt buyback operation of $5.2 billion (out of a maximum $6 billion) failed to impress, with investors holding long-term bonds.
- A 30-year bond auction sold $22 billion in debt at 5.308%, the highest yield since 2001.
- US Producer Price Inflation rose the most in three months in August, spurring bets for a Fed rate hike (75% probability according to CME FedWatch Tool).
- President Trump's proposal for a $1.3 trillion 'Trump dividend' ($5,000 per adult citizen) if Republicans win the midterms is seen as stoking fiscal deficits and rattling bond investors.
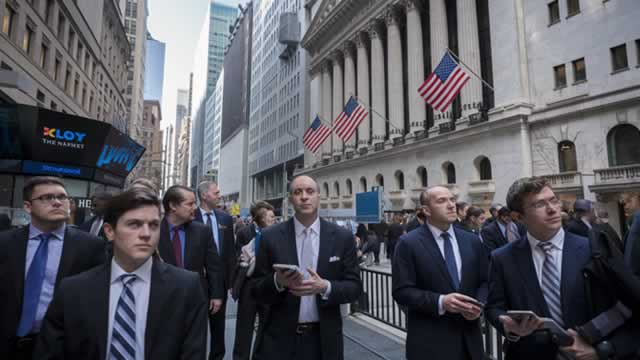
NYSE President Lynn Martin discusses the new competitive landscape with the Texas Stock Exchange (TXSE) and the overall health of the US capital markets. She highlights NYSE's strong presence in Texas and the rebound in global IPO activity, while also reflecting on the resilience of the US economy and the spirit of New Yorkers 25 years after the 9/11 attacks.
- NYSE President Lynn Martin acknowledges competition from the newly launched Texas Stock Exchange (TXSE), which recently secured its first major corporate listing.
- She highlights the strength and resilience of US capital markets, noting a significant rebound in global IPO proceeds this year, with more companies looking to go public.
- The discussion includes a remembrance of 9/11, emphasizing the enduring spirit of New Yorkers and the US economy's recovery and growth since the attacks, with the Dow opening significantly higher than on September 10, 2001.
Financial markets are showing caution ahead of the crucial US CPI data release, with Treasury yields remaining elevated and global bonds experiencing a sell-off. Persistent inflation concerns, exacerbated by record-high US diesel prices, are driving expectations for further central bank rate hikes. While some tech stocks are seeing gains, the overall macro outlook remains challenging.
- US CPI data is highly anticipated, with the 10-year Treasury yield hovering near 5% and global bonds selling off.
- US diesel prices hit a record $6/gallon, fueling inflation concerns and prompting the IEA to warn of potential demand destruction.
- Asian markets experienced declines due to inflation and oil worries, while European markets showed mixed performance.
- Analysts expect further Fed rate hikes, with one suggesting 'probably three hikes' starting next week, reinforcing a hawkish monetary policy outlook.
- Oracle (ORCL) and ACV Auctions (ACVA) saw significant premarket gains, but Adobe (ADBE) faced pressure due to AI impact fears.
The August CPI report showed headline inflation in line with expectations, but core CPI month-over-month was slightly higher. However, year-over-year core CPI reached a five-year low. Analysts believe the Fed will likely hold interest rates next week, as energy prices are the primary driver of headline inflation, which rate hikes cannot directly address.
- August CPI: Headline M/M and Y/Y were in line with estimates (0.4% and 3.4% respectively).
- Core CPI: M/M was slightly higher than expected (0.3% actual vs 0.2% estimate), but Y/Y was in line and at a 5-year low (2.4%).
- Energy prices, particularly gasoline and fuel oil, were the main drivers of the headline inflation increase.
- Analysts predict the Fed will hold interest rates next week, arguing that rate hikes won't solve energy supply shocks and core inflation is showing signs of cooling.
Jeff Currie discusses the 'dangerous phase' of the commodities rally, driven by escalating global shortages and returning Chinese demand. He highlights record US diesel prices and the potential for $5 gasoline, emphasizing that crude oil is now the primary signal, with product shortages moving upstream. Currie advocates for owning commodities as a hedge against scarcity and currency debasement.
- US diesel prices have reached a record $6/gallon, with gasoline potentially hitting $5 before the midterms.
- Shortages are moving upstream from refined products to crude oil, exacerbated by global supply chain disruptions and renewed Chinese demand.
- Commodities are identified as the best-performing asset class this year and decade, fueled by a 'toxic combination' of scarcity and currency debasement.
Komal Sri-Kumar argues the Fed should hike rates by 50 basis points to combat inflation, despite believing they might only do 25 bps or pause due to political pressure. He emphasizes the critical role of long-end Treasury yields on the economy and warns of significant headwinds for markets if yields continue to rise.
- Komal Sri-Kumar advocates for a 50 bps Fed rate hike, stating that even 25 bps would not be a 'big thing' for the market, but no change would lead to sharply rising long-end yields.
- He highlights that long-end yields (30-year, 10-year Treasuries) are more crucial for mortgages and government debt than the federal funds rate.
- He suggests the Fed chairman might be influenced by political considerations regarding rate cuts, and dismisses immediate productivity gains from AI as an inflation offset.
- He points to rising oil prices and increasing tariffs as fundamental inflationary pressures that should not be overlooked by a single CPI report.
- He warns that if the 10-year Treasury hits 5% and the 30-year hits 5.75%, it would create significant headwinds for equities, referencing past crises from unexpected rate hikes.